Post content
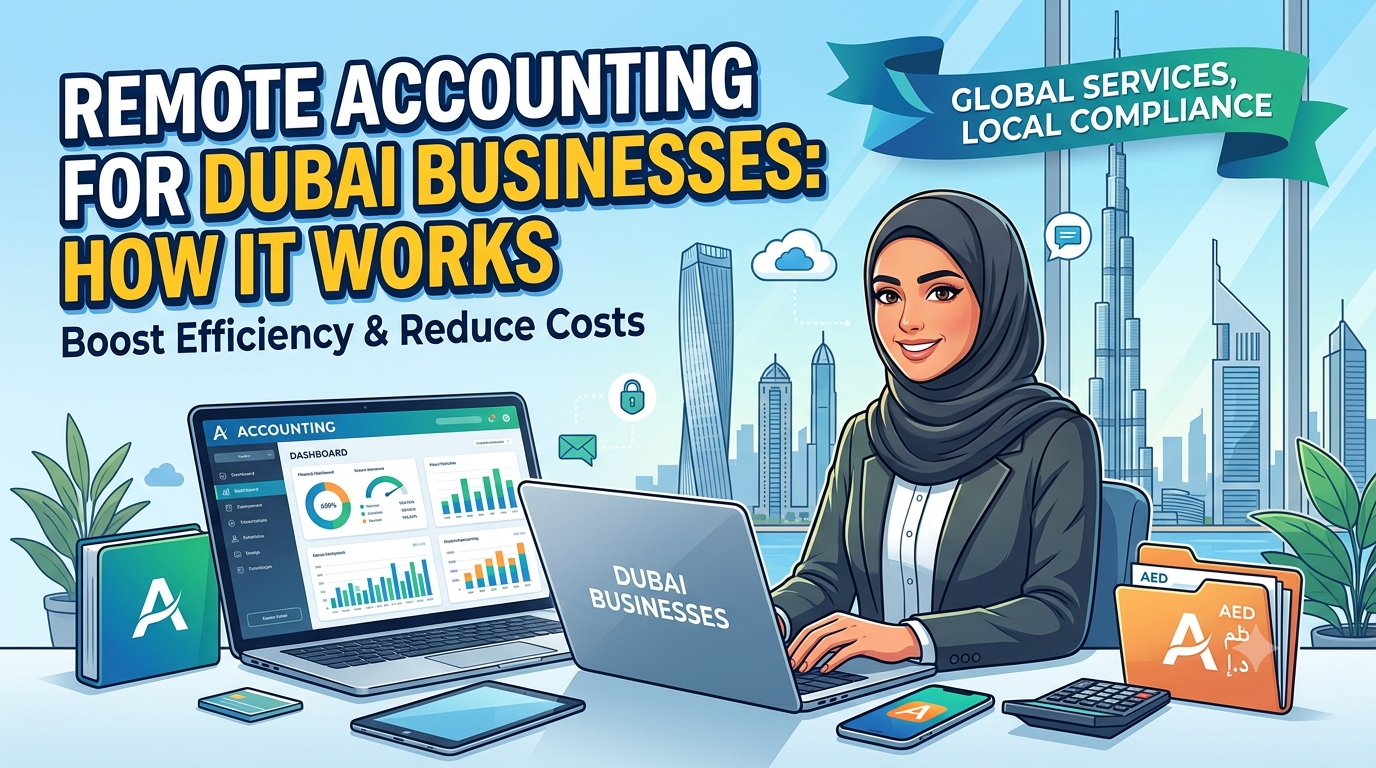
Running a business in Dubai means keeping up with VAT returns, corporate tax, audits and monthly reporting. For many owners, hiring a full-time accountant is expensive and still leaves gaps when that person goes on leave or resigns. remote accounting services in Dubai offer another route: a team of accountants works on your books online, uses cloud software and delivers reports on a fixed schedule.
What is remote accounting?
Remote accounting means your bookkeeping, financial statements and reporting are handled by an accounting team that is not sitting in your office. Documents are shared securely online, transactions are recorded in cloud software such as Zoho Books, QuickBooks or Xero, and you review the results through reports and regular calls.
What does a remote accounting team handle?
Daily bookkeeping and bank reconciliations
VAT return preparation and filing support
Corporate tax records and compliance support
Monthly financial statements and MIS reports
Payables, receivables and payroll support
Clean-up of backlog when books have fallen behind
Remote accounting vs hiring in-house
An in-house accountant costs more than the salary. You also pay for visa, insurance, end-of-service gratuity, leave tickets, software and a desk. When that one person is absent, your accounts stop. A remote team spreads the work across several people and usually charges a fixed monthly fee, so costs are easier to predict.
The trade-off is physical presence. If your business needs someone on site every day for cash handling or document collection, an in-house hire may still make sense. Many small and mid-sized companies find that a remote team covers what they need.
Is it safe to share financial data online?
It can be, if the provider takes security seriously. Ask about:
Access controls, so only the right people see your data
Encrypted cloud storage and regular backups
A signed confidentiality agreement
An audit trail showing who changed what
Never send passwords or bank logins by email. Use read-only access wherever possible.
UAE compliance: what to check
VAT in the UAE is 5%, and corporate tax applies at 9% on taxable income above AED 375,000. Rules, thresholds and deadlines can change, so always confirm the latest details on the Federal Tax Authority website. Ask any provider whether they understand UAE VAT and corporate tax, not only general bookkeeping.
How to get started
List what you need: bookkeeping, VAT, reports or all three.
Give the team access to your accounting software and documents.
Have them review your current books and flag problems.
Agree on monthly deliverables and deadlines.
Review the reports each month and ask questions.
Conclusion
Remote accounting gives Dubai businesses a team of specialists, predictable costs and reports on time, without the overheads of an in-house department. If you want to see what this would look like for your company, talk to KStar Capitals about our remote accounting services and book a short call.